
Tax reduction strategies Buffalo businesses can consider span two different areas: eligible individuals may eliminate 50% to 100% of federal capital-gains tax through Qualified Small Business Stock treatment, subject to limits, while Erie County IDA abatements through PILOTs typically last up to 10 years. Buffalo property owners receiving IDA PILOTs typically begin by paying 10 to 20 percent of their property tax bill.
When taxes affect both a business’s investment decisions and the property it occupies, the rules can be difficult to navigate. Start by identifying the relief that may apply, the conditions for eligibility, and how each option fits the business’s broader financial picture.
This article explains how capital-gains strategies work, what an IDA PILOT may change, and which details matter when assessing a project. It also looks at how tax planning can help Buffalo business owners weigh potential savings against each strategy’s commitments and constraints.
Key Takeaways
- Assess an Erie County IDA PILOT alongside the project’s property-tax impact and the terms of the proposed agreement.
- Review New York credits and deductions against the taxpayer’s circumstances, including residence, income, and the type of income or donation involved.
- Keep tax positions grounded in accurate records and applicable rules; aggressive approaches can create costly disputes and penalties.
- Buffalo homeowners with a primary residence and income up to $500,000 may qualify for Basic STAR school property tax relief, according to the New York State Department of Taxation and Finance.
- Compare the timing and trade-offs of deferring capital-gains tax with the need for access to funds and a suitable long-term plan.
Erie County IDA tax abatements and PILOTs
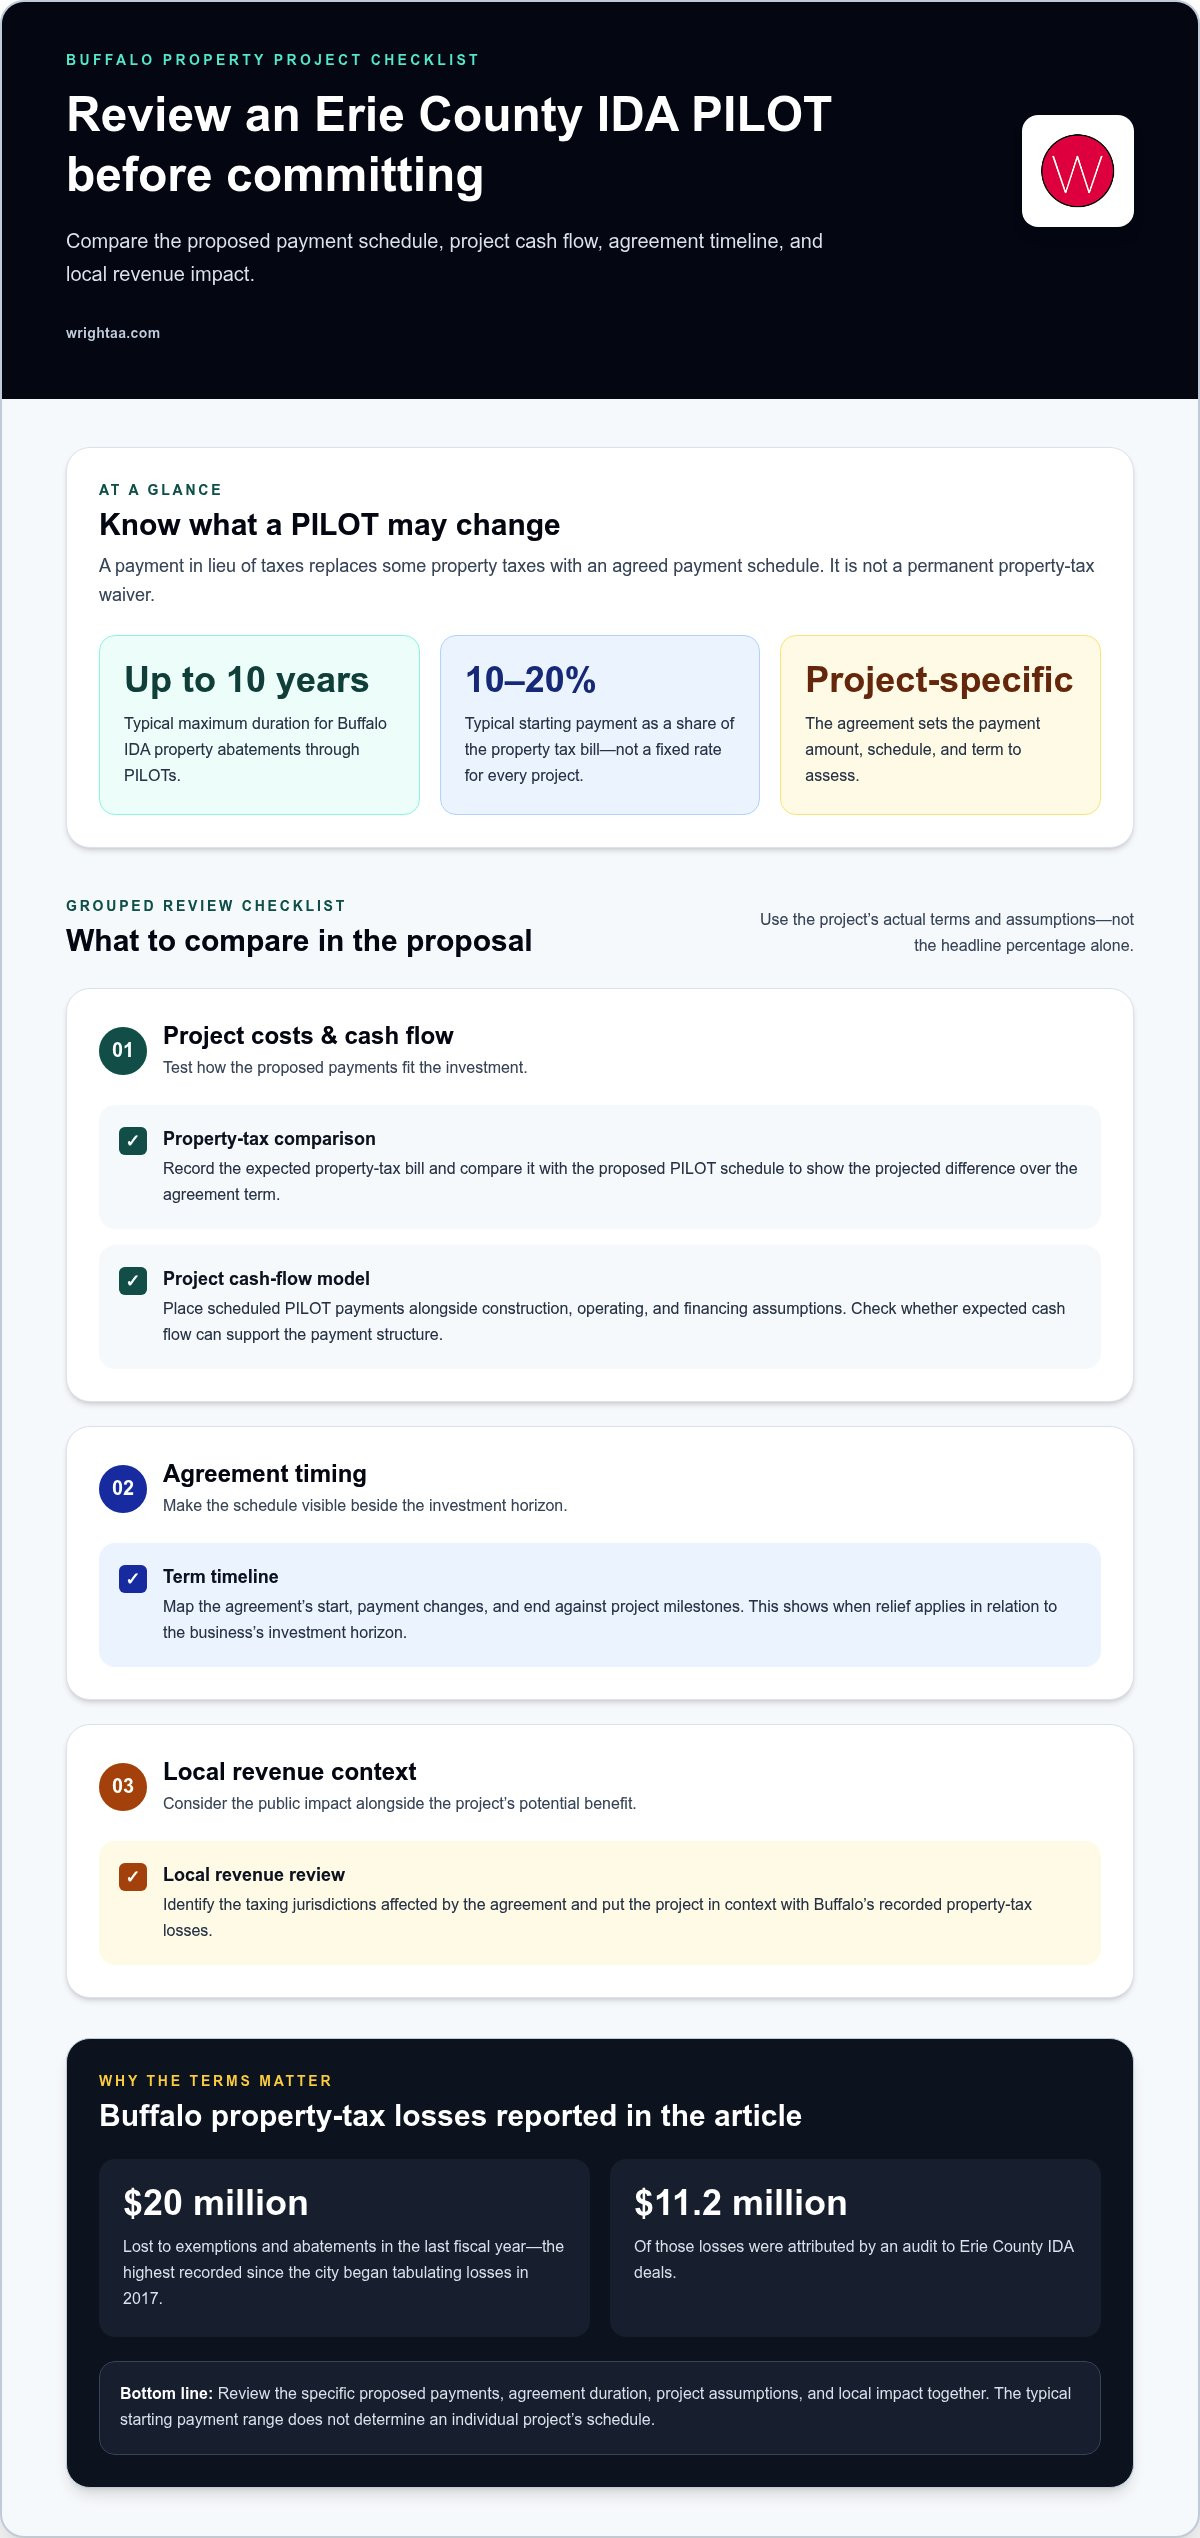
For a Buffalo business considering a property project, an Erie County Industrial Development Agency (IDA) incentive can affect the tax cost of development. A payment in lieu of taxes, or PILOT, replaces some property taxes with an agreed payment schedule. Buffalo IDA property abatements through PILOTs typically last up to 10 years. Property owners receiving them typically begin by paying 10 to 20 percent of their property tax bill.
The relief can shape a project’s operating costs, while reducing revenue available to local taxing jurisdictions. Buffalo lost $20 million in property tax revenue to exemptions and abatements in the last fiscal year. That was the highest recorded since the city began tabulating losses in 2017. An audit attributed $11.2 million of those losses to Erie County IDA deals. These figures show why incentive terms and public impact both matter in evaluating a proposal.
A PILOT is not a permanent property-tax waiver. It sets payments in place of certain taxes under a project agreement. The payment amount and schedule affect the property owner’s expected costs, while the agreement’s term determines how long the arrangement applies. For a business considering a Buffalo property, compare those payments with the project’s expected cash flow and property-tax costs.
Use these planning tools to compare the project before committing:
- Property-tax comparison: Record the expected property-tax bill and compare it with the proposed PILOT schedule. This helps show the projected difference over the agreement term.
- Project cash-flow model: Place scheduled PILOT payments alongside construction, operating, and financing assumptions. It helps test whether the project’s expected cash flow can support the payment structure.
- Term timeline: Map the agreement’s start, payment changes, and end against project milestones. This makes the timing of tax relief visible beside the business’s investment horizon.
- Local revenue review: Identify the taxing jurisdictions affected by the agreement. This puts the project’s potential benefit in context with Buffalo’s recorded property-tax losses.
These tools help owners examine costs and timing, but they don’t replace the terms of an IDA agreement. The starting payment range of 10 to 20 percent is typical, not a fixed rate for every project. An agreement can set its own schedule. A business should therefore assess the specific proposed payments, duration, and project assumptions together rather than relying on a headline percentage.
For businesses exploring tax reduction strategies Buffalo may offer, an IDA incentive is most relevant when a planned property investment fits the terms of an incentive agreement. Comparing the PILOT schedule with the property-tax baseline and projected operating cash flow can clarify the project’s potential tax effect.
What New York State income tax credits and deductions are available to Buffalo residents?
Buffalo residents should separate state income tax benefits from property tax relief. The Persons With Disabilities and Limited Income Exemption concerns a homeowner’s property, not a New York State income tax credit. Buffalo homeowners with documented disabilities and income of $58,400 or less may qualify. That distinction matters when organizing a return: property-tax relief and income-tax deductions affect different parts of a household’s finances.
One investment-related possibility is donating appreciated stock to charity. The donation may qualify for a deduction for the full amount donated, subject to applicable limits. A deduction is not the same as a tax credit, which directly reduces tax owed. Keep records identifying the stock, its value, the donation, and the receiving charity. These documents support the claimed tax treatment.
Use a brief review process to sort potential benefits before filing:
- Eligibility worksheet: Record Buffalo residence, disability documentation, and household income. It helps assess whether the $58,400 income threshold for the property exemption may apply.
- Donation record: Keep transfer details and charity documentation for appreciated stock. This tool supports review of a potential deduction and its applicable limits.
- Tax-benefit comparison: Label each item as a credit, deduction, or property tax exemption. This prevents a property benefit from being mistaken for an income-tax reduction.
For example, a Buffalo homeowner with documented disabilities and income at or below $58,400 can examine the Persons With Disabilities and Limited Income Exemption as a property-tax measure. A resident donating appreciated stock can separately review whether the gift supports a deduction, while accounting for applicable limits. These examples involve different tax categories, so combining them under a single “credit” label can obscure how each works.
Before filing, gather income records, proof of disability where relevant, property information, and stock-donation documents. Sort each item by the tax it affects and the eligibility conditions that apply. This helps clarify which benefits may be relevant and what records support a claim. For Buffalo households, separating state income-tax questions from local property-tax exemptions is a practical first step in reviewing potential relief.
Broader tax-policy examples also show why residents should identify the kind of relief involved. Buffalo's municipal analysis attributed property tax impacts to various state programs, government buildings, nonprofits, and churches; that figure concerns property-tax losses, not an individual state income-tax credit. Similar considerations apply when evaluating regional tax exemptions across Upstate New York communities, such as those found in Rochester and Syracuse, which involve distinct municipal property rules rather than personal income-tax deductions.
Other programs use different measures. The New York Power Authority's economic development programs use a 30-mile radius for their eligible municipalities, which is an eligibility boundary, not a household tax benefit. Local Payment in Lieu of Taxes (PILOT) agreements negotiated through regional industrial development agencies provide facility-specific property exemptions rather than statewide income tax credits. Investment activity offers a separate reminder: researchers estimated that investors swapped approximately $417 billion of nearly identical ETFs in the United States since 2001, including $106 billion in 2022. Such figures do not establish a deduction for any Buffalo filer; residents should rely on applicable eligibility rules and documentation, or consult professionals at Wright CPAs, LLC for guidance.
What are the risks and penalties for aggressive tax reduction strategies in New York
A tax position can fail when its paperwork and transactions don’t match. For investment losses, the Internal Revenue Service prohibits claiming a loss when an investor sells and repurchases a substantially identical investment within 30 days. A strategy involving two similar exchange-traded funds therefore needs careful review: similar holdings alone don’t establish whether the investments are substantially identical. The specific securities and transaction dates matter.
The immediate risk of violating that rule is losing the claimed investment-loss deduction. That can change the tax result reported on a return. For example, an investor who sells an ETF at a loss and repurchases a substantially identical investment within 30 days cannot claim that loss under the stated rule. Don’t treat a portfolio swap as automatically eligible simply because the fund names or indexes differ.
Use practical records to review a proposed tax position before filing:
- Trade ledger: Records each sale and purchase date, security, quantity, and proceeds. It helps identify potentially relevant transactions within the 30-day period.
- Tax-lot reconciliation: Compares broker statements with the lots reported on the return. It helps catch differences in cost basis, dates, or quantities.
- Investment comparison sheet: Sets out each fund’s holdings and index information. It helps document the reasoning behind treating two ETFs as distinct, without assuming that different names settle the question.
- Supporting-document file: Keeps trade confirmations, account statements, and calculation notes together. It helps explain how the reported loss was calculated.
These tools also expose inconsistencies before they become part of a filed return. Suppose a brokerage statement shows one sale date, while a spreadsheet uses another. The mismatch could affect whether the 30-day rule applies. Reconcile records first, then preserve the corrected calculation and the documents behind it. A clear trail makes the tax treatment easier to review.
New York taxpayers should distinguish a lawful tax choice from an unsupported claim. A deduction should reflect the actual transaction and its records, not simply the desired tax result. For a Buffalo investor considering ETF swaps, review the securities, dates, and account records together. A tax strategy review can assess whether the proposed treatment fits those facts before filing.
No single penalty amount applies to every aggressive position, and the available facts here establish no universal figure. The concrete risk addressed by the IRS rule is that an investment loss may not be claimable when the sale and repurchase involve substantially identical investments within 30 days. Sound documentation and transaction-level review help keep a tax position aligned with the activity it reports.
Strategies that
Buffalo households can examine property-tax relief alongside investment decisions. New York’s 485-a program can reduce property taxes for developers converting qualifying industrial or commercial buildings into mixed-use property that includes residential space. For a Buffalo property owner, the planned use of the building is central to assessing whether this route fits. The program connects a building’s future function with its tax treatment.
Homeowners can also review STAR relief. Buffalo homeowners with a primary residence and income up to $500,000 may qualify for Basic STAR school property tax relief, according to the New York State Department of Taxation and Finance. Homeowners age 65 or older with income of $110,750 or less may qualify for Enhanced STAR school property tax relief. These programs focus on school property taxes, rather than reducing a business’s income tax.
Other Buffalo exemptions are tied to specific household circumstances. Seniors age 65 or older with income of $58,400 or less may qualify for the Senior Citizen Low Income Exemption, which can reduce eligible homeowners’ property taxes by up to 50%. A qualifying senior who has owned and lived in a home for 25 years or more may also qualify for the Senior Citizen Longtime Resident Exemption, with household income of $35,000 or less. Qualifying veterans may receive property-tax reductions of up to 25% or more, depending on eligibility.
Investors planning tax-loss sales need a separate review. The Internal Revenue Service states that U.S. tax laws prohibit claiming an investment loss when an investor sells and repurchases a substantially identical investment within 30 days. Before selling, compare the proposed trade with recent purchases. A trade calendar can track sale and purchase dates; a holdings comparison sheet can help document which investments were considered.
These tools can organize the facts behind a decision:
- Eligibility worksheet: Record age, household income, primary-residence status, ownership history, and relevant veteran or disability documentation. It helps sort possible homeowner exemptions.
- Property-use checklist: Note the building’s current and planned uses. It helps evaluate whether a conversion may align with 485-a’s mixed-use requirements.
- Tax-lot ledger: Track investment sale and purchase dates alongside the securities involved. It helps flag trades that could fall within the 30-day wash-sale restriction.
Start by separating business-property projects, household exemptions, and investment transactions. A Buffalo developer considering residential space can assess 485-a, while a qualifying homeowner can review STAR or senior relief. An investor can use a trade calendar before completing a loss sale. This orderly review helps match each strategy to the property, household, or transaction it actually concerns.
Keep exemptions and investment trades in separate reviews. For investment losses, investors may swap similar ETFs to claim deductions while maintaining similar portfolio holdings. Investors who make ETF swaps may recognize more tax losses. A tax-lot ledger can help organize the proposed swap, relevant dates, and securities records. Keep these investment decisions distinct from household property-tax eligibility.
Deferral strategies
Deferring capital-gains tax changes when tax is paid; it doesn’t automatically erase the liability. The value comes from keeping funds invested instead of paying tax immediately. One estimate says deferral can add about 2-5% per year in after-tax wealth. The result depends on the investment’s performance, the length of deferral, and the tax due when gains are recognized. For a Buffalo business owner planning a sale, those factors shape whether preserving capital now supports the next stage of a plan.
Consider the example’s assumptions carefully. Investing a deferred tax liability at an assumed 8% annual return for 10 years produces $2.93m after tax. Selling immediately, paying tax, and investing the proceeds for 10 years would require a 10.08% annual return to reach the same after-tax result. These figures illustrate a specific comparison, not a forecast. The difference reflects the effect of keeping more capital invested during the deferral period.
Two structures can involve deferral, with different commitments and cash-flow patterns. An exchange fund typically requires a 7-year time commitment before investors receive a diversified stock portfolio. A charitable remainder trust defers capital-gains tax until gains are distributed to the beneficiary. Grantor distributions are typically scheduled over 2-20 years, which affects when funds may be received and taxed.
- Deferral timeline: Maps when a gain may be recognized and when tax payments may arise. It helps compare timing with planned business or personal cash needs.
- After-tax projection: Models investment assumptions alongside potential tax payments. It helps compare a deferral scenario with an immediate sale, as in the 8% and 10-year example.
- Distribution schedule: Tracks expected trust distributions. It helps show how a 2-20-year payout pattern may align with future cash needs.
- Commitment calendar: Records the exchange fund’s 7-year holding period. It helps investors consider whether that time horizon fits their liquidity plans.
Before choosing a structure, identify the gain, intended investment horizon, and need for access to funds. Compare the tax timing and cash-flow effects using consistent assumptions. A longer deferral may keep capital invested longer, while a longer commitment may reduce flexibility. These trade-offs matter alongside the projected tax effect.
For a structured review of capital-gains timing, discuss tax strategy for deferral alongside your investment horizon and cash-flow needs.
Wright CPAs: Tax Planning and Preparation
Wright CPAs, LLC helps Buffalo business owners connect tax decisions with the records and cash flow behind them. Its Tax Planning and Preparation services can support owners assessing capital gains, property-related decisions, and tax obligations before filing. Consider tax planning before a major transaction or investment decision that could affect the business’s tax position.
Accurate bookkeeping and payroll records provide a clearer foundation for those discussions. CFO Services can help owners consider how tax timing fits into broader financial decisions. The goal is a deliberate view of the business, its obligations, and the choices ahead.
To discuss your business’s tax planning needs, contact Wright CPAs, LLC.
Build a Tax Plan Around What Comes Next
Connect tax choices with the business decisions they affect. A property investment, potential asset sale, or staffing change can each influence the timing and form of tax obligations. Consider these decisions together rather than as isolated filing questions. This broader view can make tax reduction strategies in Buffalo part of a deliberate plan for the business’s next stage.
Wright CPAs, LLC offers Tax Planning and Preparation, Bookkeeping, and Payroll Services. These services help owners align tax decisions with financial records and payroll activity. Begin planning before a major transaction or structural change, while there is time to assess the effects and plan accordingly.
Bring your questions and the decisions ahead into a focused conversation. Contact Wright CPAs, LLC to discuss a thoughtful path forward. With a clearer view of the choices in front of you, you can move ahead with greater confidence.
Frequently Asked Questions
What tax incentives are available to Buffalo small businesses and self-employed workers?
Buffalo small businesses can examine Erie County IDA PILOTs for qualifying projects, the 485-a property-tax reduction for qualifying conversions to mixed-use property with residential space, and Qualified Small Business Stock treatment for eligible investors. QSBS may eliminate 50% to 100% of federal capital-gains tax, subject to limits. Self-employed workers should separate business deductions from property or investment relief, then match each claim to the relevant asset, transaction, and supporting records.


